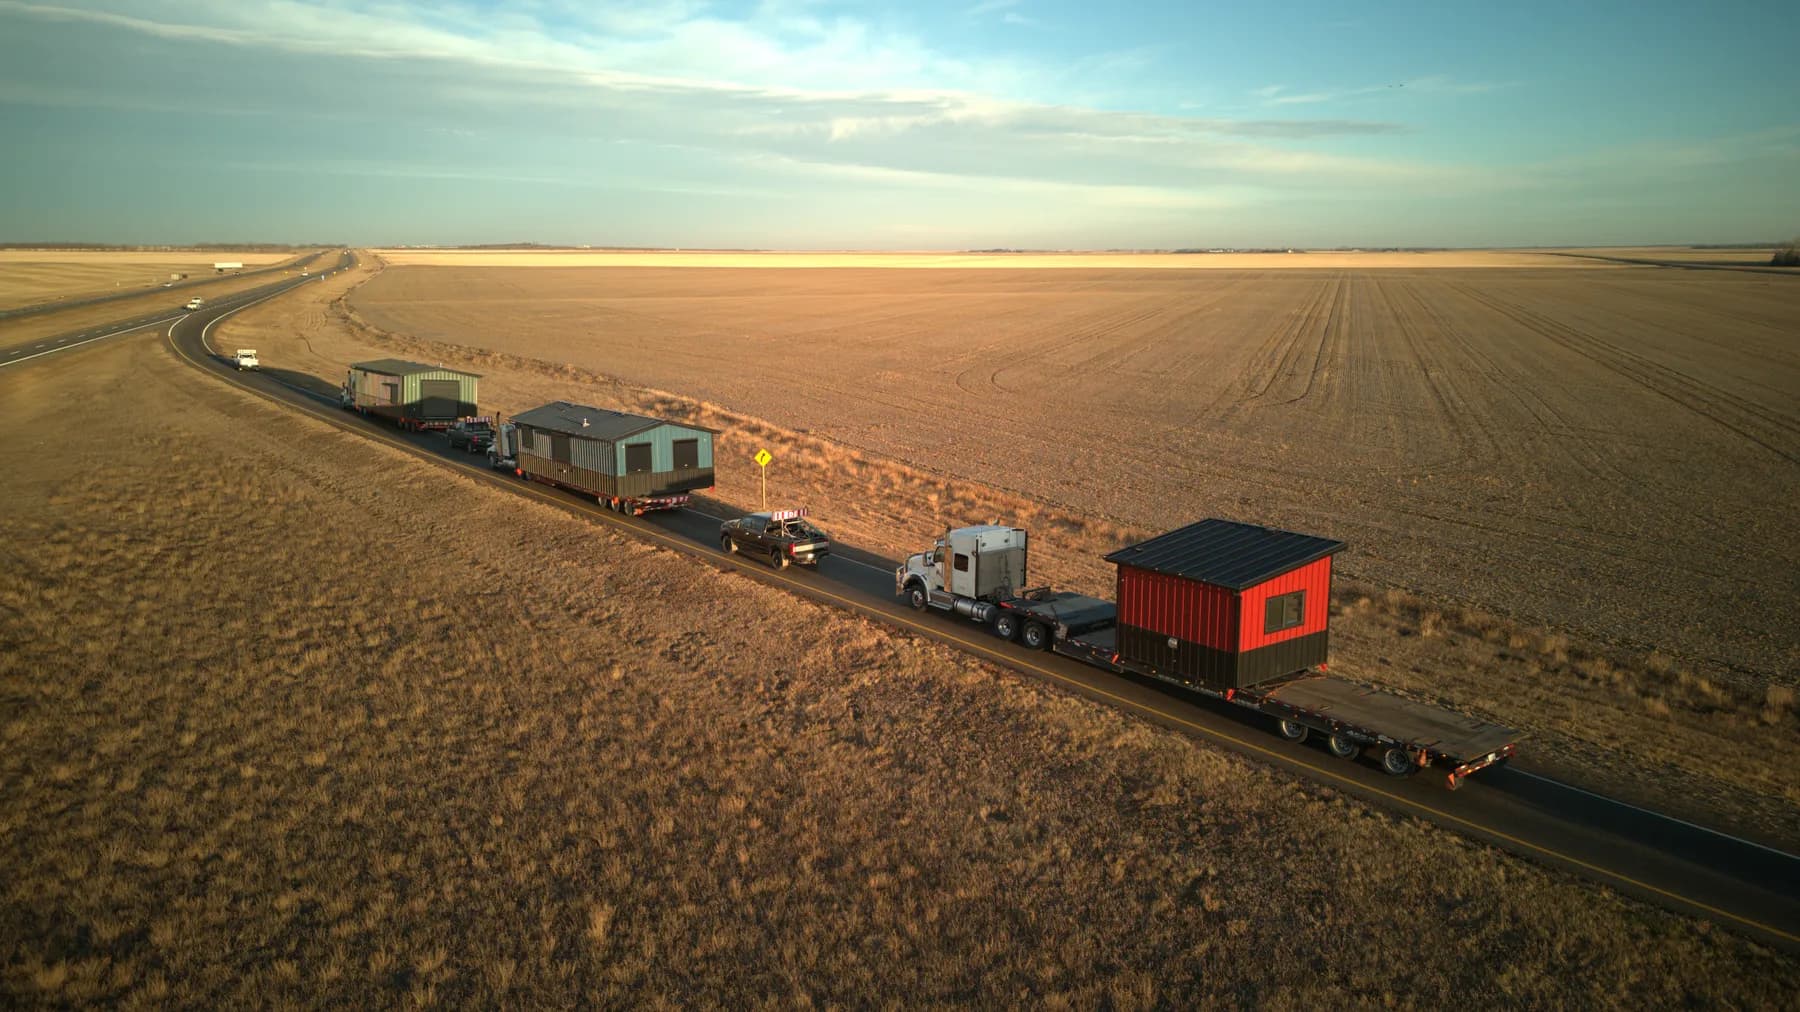
Once a modular home is set on a permanent foundation it is real property, and it is insured the same way as a site-built house. What is different is the few weeks before that: a finished house is built in a plant, carried by road and lifted onto your foundation, and your broker needs to know who covers it at each of those steps.
Insurance is one of the lines on Herauf's budget planner, which separates what Herauf prices from what you buy from other people. Paying for the build itself is covered in financing a modular home. This article is the insurance side, stage by stage.
Is a modular home insured like any other house?
Yes, once it is on its foundation. A modular home built to meet or exceed CSA A277 and set on a permanent foundation is real property: appraised, mortgaged and insured like any house. That is the practical difference from a manufactured home, which is often treated as personal property (chattel) unless it is permanently affixed and its chassis title retired. The full comparison is on modular vs RTM vs manufactured.
What does home insurance cover, and what sets the price?
According to the Financial Consumer Agency of Canada, a home policy may cover damage to or loss of the house, damage to or theft of your belongings, and your liability if someone is hurt on your property. Insurers price it on the type of home, what it is built of, its age, size and location, its replacement value, how far it is from a fire hydrant or fire station, your claims history and your deductible.
Two of those matter more than usual for a factory-built home on a rural lot. Distance to a hydrant or fire hall is often greater on an acreage, so ask how it affects the premium before you choose the site. And ask whether a claim is settled at replacement value, the cost to replace after a covered loss, or at actual cash value, which is the cost new minus depreciation.
Who insures the home before it is on the foundation?
Settle this before you sign, with both your builder and your broker, because it depends on the contract. Herauf's budget planner lists insurance while the home is being built as your line, arranged through your broker, and gives you the exact question to ask: what cover do you need on a factory-built home in transit and during the set? Delivery and setting the home on your foundation are Herauf's lines, so ask Herauf the matching question: at what point does the home become yours to insure?
What does the insurer or lender want to see?
Proof of how the home was built. Herauf's price includes the factory inspection and code documents your lender and insurer will ask for, and they are worth keeping for resale too. Useful details for the broker: the home meets or exceeds CSA A277, the residential models are energy-modelled for climate zones 6 through 8, electric heat is standard and the windows are triple-pane. What comes standard lists the rest.
If you finance through CMHC Prefab Plus, funds are released in stages: one for the land and site preparation, one when the home is delivered, and later ones for installation and finishing. Ask your lender what proof of insurance it needs at each draw, so cover is in place before the money moves.
When should you call your broker?
At quote stage, not delivery week. Bring the written quote, the site address and the delivery window, and ask three things: what covers the home in transit and during the set, when the house policy starts, and how the rural location affects the premium. Then use the budget planner to put a number beside every line that is yours, or ask for a free written quote from Herauf, usually back within one business day.
Sources
- Financial Consumer Agency of Canada, Home insurance
- Canada Mortgage and Housing Corporation, CMHC Prefab Plus
Common questions
Is a modular home insured differently from a site-built house?
Not once it is set. A modular home on a permanent foundation is real property, appraised, mortgaged and insured the same way as a site-built house. The questions that differ are about the weeks before that: the build, the move and set day.
Who insures a modular home while it is being built and delivered?
Ask both your builder and your insurance broker before you sign, because it depends on the contract. Herauf's budget planner lists insurance while the home is being built as the buyer's line, and the question to put to your broker is what cover you need on a factory-built home in transit and during the set.
What does an insurer look at when pricing home insurance?
According to the Financial Consumer Agency of Canada, insurers consider the type of home, its materials, age, size and location, its replacement value, the distance to a fire hydrant or fire station, your claims history and the deductible you choose.
A Herauf modular home on a prairie road